2026 SMSF Property Updates
A single tweak in superannuation rules can turn a promising property acquisition into an onerous compliance burden.
For many Australians, a self-managed super fund (SMSF) is still a popular vehicle for acquiring real estate, thanks to concessional tax treatment, direct control over assets, and potential long-term growth. But in 2026, SMSF property investing is less about enthusiasm and more about rigorous planning.
These days, prospective buyers must ask not just “Can I buy through my SMSF?” but “Does the fund’s structure, cashflow and compliance framework truly support my retirement goals?”
Why SMSF Property Still Appeals
- Direct decision-making authority
- Exposure to residential or commercial real estate
- Concessional tax treatment on earnings
- Potential rental income within the fund
- Capital growth over the long term
Commercial assets may allow a related business to lease office or industrial space at market rates, while residential properties often benefit from steady tenant demand. In 2026, the difference between success and failure is in the details, not the headline tax rate.
The most resilient SMSF property strategy isn’t the one with the highest gearing; it’s the one that weathers scrutiny, cost increases, and vacancies.
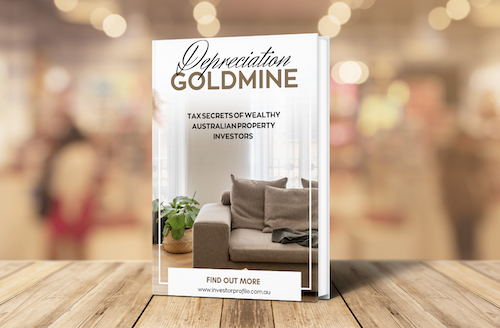
Discover the #1 tax secret wealthy Australian property investors use to grow their portfolios faster — even in a high interest rate environment.
- Learn how to turn wear and tear into wealth
- See real examples of $15,000+ first-year deductions
- Understand how to structure your purchases for maximum after-tax ROI
Download Your Free Wealth Building Guide
This ebook reveals how to legally slash your tax bill while building long-term wealth through property. Learn the strategies savvy investors use to gain an edge — even before settlement.
Free Instant Access
- Maximise tax deductions and improve cash flow
- Understand Division 40 vs 43 and how to claim both
- Position yourself to reinvest and scale faster
Key SMSF Property Rules
Sole Purpose Test
Every SMSF must exist solely to provide retirement benefits. Trustees must not:
- Live in fund-owned residential property
- Allow family or friends to occupy it
- Acquire real estate for immediate personal use
Related-Party Restrictions
Residential
An SMSF generally cannot:
- Purchase residential real estate from a related party
- Lease residential property to a related party
Commercial
Commercial property that qualifies as business real property can be bought from or leased to a related party, provided all terms are at arm’s length and reflect market value.
Limited Recourse Borrowing Arrangements (LRBAs)
Most SMSF property loans are set up as LRBAs, meaning:
- The loan secures only the single asset being acquired
- If the fund defaults, the lender’s claim is limited to that asset
- Interest rates and fees are usually higher than retail investment loans
- Borrowing serviceability requirements are stricter
LRBAs offer access to property, but they heighten the importance of liquidity reserves, contribution planning and tenant stability.
2026’s Biggest Impacts
1. Heightened Compliance Focus
The ATO is scrutinising trustee conduct, documentation, valuations and whether investments align with the written strategy. Expect checks on:
- Current market appraisals
- Related-party transaction evidence
- Loan and lease contracts
- Liquidity management records
- Annual strategy reviews
2. Documentation Beyond Box-Ticking
Paper-based governance must demonstrate genuine decision-making:
- Yearly investment strategy updates
- Insurance cover assessments
- Cashflow and liquidity planning
- Independent valuations where needed
- Trustee minutes for major decisions
3. Ongoing Cashflow Pressures
Even if interest rates soften, SMSF loans remain more conservative. Lenders often demand larger deposits and stronger serviceability buffers.
| Factor | Personal Investment Loan | SMSF LRBA |
|---|---|---|
| Typical deposit | 10–20% | 20–30%+ |
| Interest rate | Lower | Higher |
| Repayment support | Household income | SMSF rent + contributions |
Example for an $800,000 purchase:
- Deposit (30%): $240,000
- Loan: $560,000
- Annual interest @7%: ~$39,200
- Gross rent @ $850/week: ~$44,200
That may cover interest, but don’t forget property management fees, maintenance, insurance, accounting and potential vacancies.
Residential vs Commercial SMSF Property
Residential
- Pros: Easy to understand, broad tenant demand
- Cons: No related-party leases, off-limits for members or relatives
Commercial
- Pros: Possible related-party tenancy, strong strategic fit for business owners
- Cons: Longer vacancies, tenant concentration risk
Liquidity Risks
SMSFs heavily invested in property must still keep enough cash for:
- Pension payments
- Audit and accounting fees
- Insurance premiums
- Repairs and maintenance
- Compliance or legal costs
A fund may look wealthy on paper with 90% in real estate but can be operationally fragile.
Four Pre-Purchase Questions
- Can the fund handle 6–12 months of vacancy?
- Can it absorb a major unexpected repair?
- Will pension payments force a distressed sale?
- Is concentration risk appropriate given member ages?
Tax Benefits: Attractive but Conditional
| Tax Area | SMSF Treatment | Impact |
|---|---|---|
| Rental income | 15% in accumulation | Boosts net returns |
| Capital gains (held >12 months) | Effective 10% after discount | Rewards long-term owning |
| Retirement-phase income | Potentially tax-exempt | Improves drawdown outcomes |
These perks vanish if the fund breaches non-arm’s-length or related-party rules.
2026 SMSF Property Checklist
Before Purchase
- Review investment strategy
- Confirm cash-reserve buffers
- Stress-test loan repayments and vacancies
- Get advice on related-party rules
- Match asset type to retirement timeline
After Purchase
- Use market-rate lease terms
- Keep detailed trustee minutes
- Update valuations annually
- Monitor concentration risk
- Reassess liquidity each year
Final Takeaway
SMSF property in 2026 remains a viable path to retirement wealth—but only for funds that are rigorously structured, well-documented and funded with realistic cash buffers. If you treat your SMSF like a regulated vehicle rather than a tax shortcut, property can be a powerful long-term play. If not, hidden compliance and liquidity costs can outweigh any concessional rate.
References
- ATO – SMSFs and property
- ATO – Sole Purpose Test
- ATO – Non-arm’s-length income
- ASIC – SMSFs
- APRA – Super statistics
This article is general information only and does not constitute financial, tax or legal advice.