May 14th, 2025

Can You Add Lenders Mortgage Insurance (LMI) to Your Loan? Here's What You Need to Know

Lenders Mortgage Insurance: A Smart Option for Homebuyers

Lenders Mortgage Insurance (LMI) is a cost that many buyers with less than a 20% deposit encounter. The good news is you don’t always have to pay it upfront. In Australia, numerous lenders offer the option to add the LMI premium to your home loan, helping you maintain healthier cash flow at the time of purchase.

How It Works

When you decide to include LMI in your loan, the premium becomes part of your overall borrowing. Instead of paying the fee as a lump sum at settlement, you repay it gradually along with your standard mortgage repayments.

Impact on Borrowing and Repayments

Although adding LMI to your loan minimizes your upfront costs, it does increase both the total loan amount and the interest you will pay over time. For instance:

  • Loan Amount: $450,000
  • LVR: 90%
  • Estimated LMI Rate: 2.4%
  • LMI Premium: $450,000 × 2.4% = $10,800
  • New Loan Amount: $460,800 (plus any applicable stamp duty on the LMI premium)

This slight increase in your monthly repayments can also affect your borrowing power if you’re already approaching lender limits.

Other Considerations

  • Stamp Duty on LMI: In some states, stamp duty may apply to the LMI premium. Be sure to verify the details with your broker or use an online calculator.
  • Talk to Your Lender Early: If you plan to add LMI to your loan, it’s wise to inform your lender or broker during the application process.

Final Thoughts

Including LMI in your home loan can be a practical strategy to enter the property market sooner. Just ensure you weigh the long‐term costs against the benefits of saving up for a larger deposit.
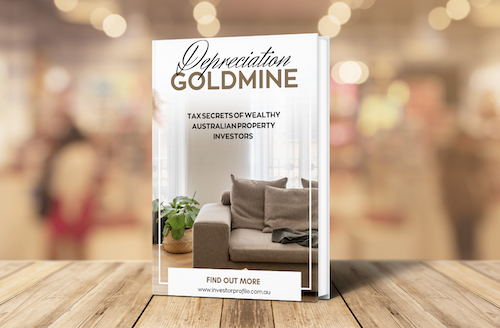
Depreciation Guide

Discover the #1 tax secret wealthy Australian property investors use to grow their portfolios faster — even in a high interest rate environment.

  • Learn how to turn wear and tear into wealth
  • See real examples of $15,000+ first-year deductions
  • Understand how to structure your purchases for maximum after-tax ROI

Download Your Free Wealth Building Guide

This ebook reveals how to legally slash your tax bill while building long-term wealth through property. Learn the strategies savvy investors use to gain an edge — even before settlement.

  • Maximise tax deductions and improve cash flow
  • Understand Division 40 vs 43 and how to claim both
  • Position yourself to reinvest and scale faster
Free Instant Access

Would you like a personalized repayment breakdown, including LMI for your scenario?
@

Unlock the power of property depreciation and keep more of your hard-earned cash! Learn how this often-overlooked strategy can significantly reduce your tax bill and boost your investment returns. Whe...

@

Harry Triguboff didn’t just build apartments — he rewrote the rules of Australian real estate. From eight units in the suburbs to over 75,000 across Sydney, Brisbane, and the Gold Coast. While most ch...

@

Still waiting for a sign to invest in property? Jesus fed the 5,000 — but He didn’t hand out investment portfolios. The wealthy aren’t waiting for miracles. They’re claiming deductions, leveraging e...

You may also like

Related posts

Top Tools for Maximizing Property Depreciation Deductions in Australia

Maximizing Depreciation Deductions on Investment Properties Professionals such as quantity surveyors, accountants, and property investors depend on specialized tools and resources to calculate and leverage depreciation deductions for new investment properties in Australia. Understanding and utilizing these resources can significantly reduce taxable income while ensuring compliance with ATO guidelines. Essential...

May 25th, 2025
1 year ago
Move Back In or Keep Renting? CGT and Tax Insights for Melbourne Property Investors

Should You Move Back In to Preserve Your Six-Year CGT Exemption? For Australian property investors, the decision to return to a former home versus keeping it rented out can carry substantial financial and tax implications—especially around Capital Gains Tax (CGT). If you occupied a property, then rented it from 2019,...

Jun 4th, 2025
1 year ago
Borrowing Power Assessment for Joseph (NT, Self-Employed)

Borrowing Power Assessment for Joseph (NT, Self-Employed) Snapshot of Financial Position Detail Amount / Notes Age 49 Employment Self-employed (ABN held for 5 years) 2024 FY Income $300,000 (Declared on NOA) Rent Paid $550 / week Savings / Deposit $50,000 Superannuation Joseph: $140,000Partner: $70,000 Credit Cards 1 card (limit $7,000)...

Jul 20th, 2025
1 year ago
Straightforward process

Ready to take control of your financial future?

01
Discovery Q&A:

We begin with a personalized discovery Q&A to understand your goals, risk tolerance, and financial situation.

02
Custom Strategy:

Based on your needs, we craft a strategic investment or financial plan tailored just for you.

03
Ongoing Support:

We help you track progress, optimize decisions, and adjust your plan as your life and markets evolve.

04
Financial Freedom:

With a clear roadmap and expert guidance, you move confidently toward long-term wealth and peace of mind.

28+ Years guiding investors
Plan Your Investment Strategy

Understand your goals and build a tailored strategy—whether you're focused on cashflow, capital growth, or long-term wealth creation.

Access the Right Opportunities

Explore high-growth areas, new builds, house & land packages, or SMSF-ready properties matched to your financial profile.

Build Long-Term Wealth

Leverage tax advantages, depreciation, and smart lending strategies to maximise returns and grow your portfolio sustainably.

Start Your Investment Journey

Smart Property Investing Starts Here

Whether you're a first-time investor or growing your portfolio, we provide the guidance, tools, and insights you need to make informed decisions and secure high-performing properties. Let us help you turn property into prosperity.