Jul 22nd, 2025

Can You Get a Home Loan with ATO Debt in Australia?

Mortgage and ATO Debt

Securing a Home Loan With ATO Tax Debt

Applying for a mortgage is complicated enough, but if you owe money to the Australian Taxation Office (ATO), the process becomes even more challenging. Many Australians ask: Can I still get a home loan with ATO debt? The answer is yes, provided you meet certain criteria.

Why ATO Debt Raises Concerns

Lenders view outstanding tax liabilities as a red flag, signaling potential cash flow issues. Major banks in particular often refuse to approve loans unless your ATO debt is settled or formalised through a payment plan.

Major Banks: Strict Requirements

Most big banks will:

  • Decline applications if the debt is unpaid.
  • Require a documented payment schedule if you’re on a repayment plan.
  • Ask for evidence of regular repayments and confirmation that the ATO hasn’t taken legal action.

In many instances, banks insist the ATO debt is cleared prior to or at settlement.

Specialist and Non-Bank Lenders: More Flexibility

Non-Bank Lender

Non-bank and specialist lenders often cater to borrowers with complex financial backgrounds. They may offer a home loan despite ATO debt, albeit under stricter conditions:
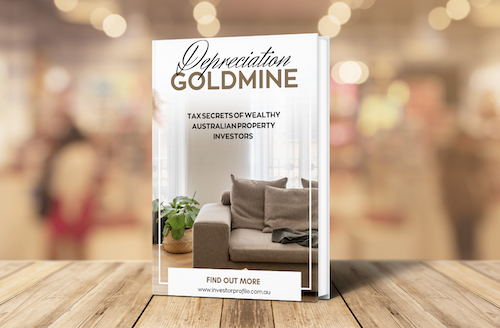
Depreciation Guide

Discover the #1 tax secret wealthy Australian property investors use to grow their portfolios faster — even in a high interest rate environment.

  • Learn how to turn wear and tear into wealth
  • See real examples of $15,000+ first-year deductions
  • Understand how to structure your purchases for maximum after-tax ROI

Download Your Free Wealth Building Guide

This ebook reveals how to legally slash your tax bill while building long-term wealth through property. Learn the strategies savvy investors use to gain an edge — even before settlement.

  • Maximise tax deductions and improve cash flow
  • Understand Division 40 vs 43 and how to claim both
  • Position yourself to reinvest and scale faster
Free Instant Access
  • Lower Loan-to-Value Ratio: Typically capped at 85–90%.
  • Higher Interest Rates: Reflecting the increased lender risk.
  • Strong Income Proof: Consistent, verifiable income statements or BAS documents.
  • Full Disclosure: Detailed information on your ATO debt and repayment history.
  • No Legal Action: The ATO must not have lodged a caveat or initiated recovery proceedings.

Refinancing to Cover ATO Debt

If you have enough equity in your property, some non-bank lenders allow you to refinance your existing mortgage to pay out the ATO debt. This debt consolidation strategy often requires full documentation and strong serviceability checks.

Serviceability and Capacity

Lenders will count your tax repayment plan as part of your monthly liabilities, which can reduce your maximum borrowing limit and narrow your lender options.

Credit and Legal Implications

While ATO debt doesn’t typically appear on your personal credit report, the ATO can lodge caveats or issue Director Penalty Notices, which lenders will detect during a property search. Expect requests for recent bank statements or BAS filings to confirm there are no hidden liabilities.

Key Takeaways

  1. Be Transparent: Disclose your ATO debt early to your broker or lender.
  2. Gather Documentation: Provide payment plans, tax returns, and bank statements.
  3. Explore Specialist Lenders: They’re more open to borrowers with tax debts.
  4. Consider Refinancing: Use home equity to consolidate ATO debt when possible.

Need expert advice? Speak to a mortgage specialist who understands the lender landscape and can help structure your application.

References
1. ATO Debt Home Loan Guide
2. Piper Alderman: ATO Payment Plan Dangers
3. Money: Business Tax Debt Loans

@

You see a living room — they see lending leverage. Property investing isn’t about vibes, it’s about structure. Know your LVR. Extract equity. Play the bank’s game better than they do. #LendingLev...

@

Investing in the city doesn’t mean buying in the CBD. It means understanding where the next wave of growth is happening. Fringe suburbs—just outside the city core—are where infrastructure, population,...

@

They view money as a tool for freedom, not a trophy for status. They focus on studying patents and building systems, rather than reacting to market headlines and developing habits. Wealth is not a mat...

You may also like

Related posts

Maximize Property Investment Returns: Depreciation Deductions for a $700,000 New Build in Australia

Maximise Your Property Depreciation Benefits in Australia For Australian property investors, depreciation offers a valuable tax saving, especially on newly built assets. You can claim deductions under two main categories: Capital Works (Division 43) and Plant & Equipment (Division 40). Depreciation Categories Capital Works (Division 43) Structural components (walls, roofing,...

Jun 4th, 2025
1 year ago
What Happens When You Turn Your Home into an Investment Property in Australia (2025 Guide)

Should You Switch Your Home Loan When Renting Out Your Home? Considering renting out your principal place of residence (PPOR) in Australia? It’s not just about finding tenants and collecting rent. There are important financial and legal factors to consider, especially concerning your mortgage. Why You Need to Update Your...

May 25th, 2025
1 year ago
How Simon Can Afford a $700,000 Investment Property at 62

Maximizing Simon’s Borrowing Power for a $700,000 Investment Property Simon is 62 and has a combined annual income of $109,200: $52,000 from employment, $36,400 from income protection, and $20,800 from renting a granny flat. He owns a Mudgereeba home valued at $1.3 million with a $500,000 mortgage, leaving $800,000 in...

Jul 30th, 2025
1 year ago
Straightforward process

Ready to take control of your financial future?

01
Discovery Q&A:

We begin with a personalized discovery Q&A to understand your goals, risk tolerance, and financial situation.

02
Custom Strategy:

Based on your needs, we craft a strategic investment or financial plan tailored just for you.

03
Ongoing Support:

We help you track progress, optimize decisions, and adjust your plan as your life and markets evolve.

04
Financial Freedom:

With a clear roadmap and expert guidance, you move confidently toward long-term wealth and peace of mind.

28+ Years guiding investors
Plan Your Investment Strategy

Understand your goals and build a tailored strategy—whether you're focused on cashflow, capital growth, or long-term wealth creation.

Access the Right Opportunities

Explore high-growth areas, new builds, house & land packages, or SMSF-ready properties matched to your financial profile.

Build Long-Term Wealth

Leverage tax advantages, depreciation, and smart lending strategies to maximise returns and grow your portfolio sustainably.

Start Your Investment Journey

Smart Property Investing Starts Here

Whether you're a first-time investor or growing your portfolio, we provide the guidance, tools, and insights you need to make informed decisions and secure high-performing properties. Let us help you turn property into prosperity.