Securing a Home Loan with a Personal Loan Deposit
In Australia, it’s possible to use a personal loan as part or all of your home loan deposit. This approach can be useful for high-income earners who haven’t built up savings yet, but lenders will scrutinise your serviceability, debt-to-income ratio and overall financial discipline.
Can You Use a Personal Loan for a Home Loan Deposit?
Yes. Some Australian lenders will accept personal loan funds as deposit, but policies vary between institutions. Always check with your broker or lender before proceeding.
How It Works
- Apply for a Personal Loan
Personal loans typically range from $2,000 to $75,000 over 1–7 years. Rates depend on your credit score, income and whether the loan is secured or unsecured.
- Secured loans: from 5.90% p.a. (e.g. MoneyPlace)
- Unsecured loans: 5.76%–13.87% p.a.
- Use Funds as Deposit
Once approved, the loan proceeds hit your account. You then allocate these funds towards your home deposit. Full disclosure of the personal loan is required when you apply for the mortgage. - Apply for Your Home Loan
Your mortgage lender will assess your ability to manage both repayments. Key factors include:
- Income level
- Credit score (preferably 670+)
- Existing debts and living expenses
- Loan-to-Value Ratio (LVR)
- Manage Repayments
You’ll service both loans simultaneously. Paying off the personal loan sooner can reduce interest costs.
Key Considerations for High-Income Earners with No Savings
- Lender Scrutiny: No savings may signal risky money habits.
- Higher LVR: Deposits under 20% often trigger Lenders Mortgage Insurance (LMI).
- Eligibility: You must meet minimum income and residency criteria.
- Over-leveraging Risk: A strong salary doesn’t override high debt-to-income ratios.
Alternatives to Personal Loans
- Guarantor loans (family member backs your deposit)
- Secured equity (using a car or other asset)
- Low-deposit mortgages (some require as little as 5%)
- Gifted deposits (must be declared as non-repayable)
Realistic Scenario
Income: $150,000/year, no savings. You borrow $30,000 for deposit.
- Personal loan repayment: ~$950/month at 10% p.a.
- Home loan repayment: ~$3,400/month at 6% p.a. (on $570,000 loan, 95% LVR)
- Total outgoing: ~$4,350/month
With a solid debt-to-income ratio and low living costs, this can work—but you’ll need detailed proof of income and expenses.
Final Tips
- Use comparison tools (Finder, Canstar, MoneyMe) to find competitive rates.
- Boost your credit score: pay bills on time and avoid multiple loan applications.
- Consider secured loans if you own an asset to access lower rates.
- Speak to a mortgage broker for lender-specific guidance.
- Budget ahead and build a small buffer to strengthen your application.
Need help navigating your options? Chat with a loan strategist to discover the best path to homeownership, even without savings.
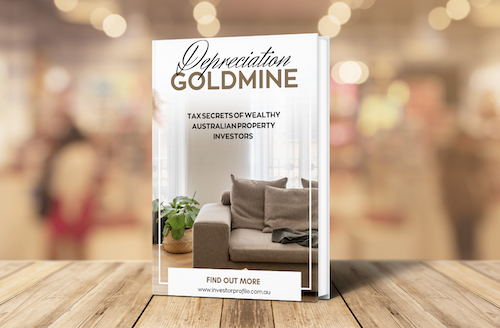
Discover the #1 tax secret wealthy Australian property investors use to grow their portfolios faster — even in a high interest rate environment.
- Learn how to turn wear and tear into wealth
- See real examples of $15,000+ first-year deductions
- Understand how to structure your purchases for maximum after-tax ROI
Download Your Free Wealth Building Guide
This ebook reveals how to legally slash your tax bill while building long-term wealth through property. Learn the strategies savvy investors use to gain an edge — even before settlement.
- Maximise tax deductions and improve cash flow
- Understand Division 40 vs 43 and how to claim both
- Position yourself to reinvest and scale faster
Disclaimer: This information is for educational purposes only. Consult a qualified financial adviser before making any loan decisions.