Jul 23rd, 2025

How Sally Can Afford a $650,000 Property: A Strategic Guide to Boosting Borrowing Power

Sally’s Path to Home Ownership

How Sally Can Secure a $650,000 Home

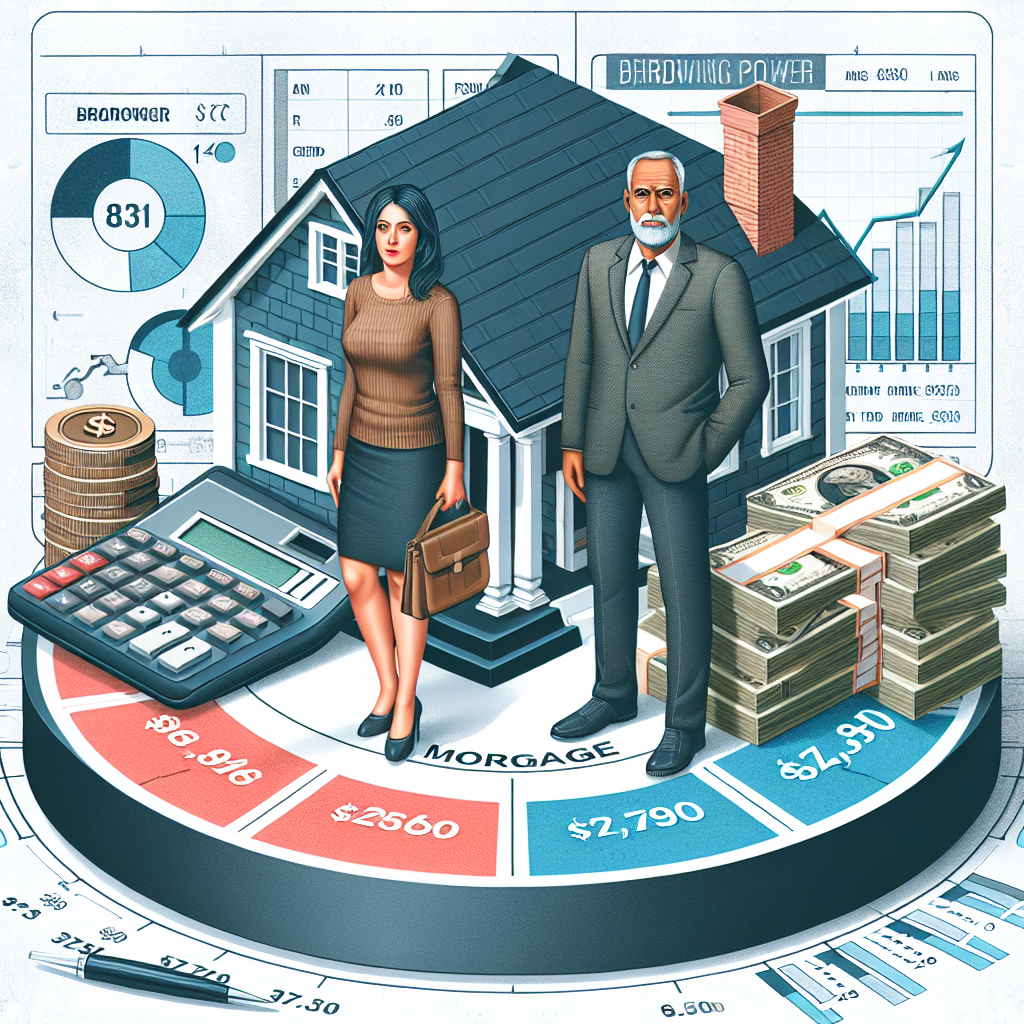
Sally is a self-employed tutor whose annual income rose from $60,000 in 2024 to $120,000 in 2025. As a single parent with one child, she currently holds a $420,000 mortgage on a property valued at $930,000. She also carries a $20,000 ATO debt and has $15,000 in savings.

Current Financial Snapshot

  • Average Assessable Income: ~$90,000 over two years, likely reduced by lenders to ~$72,000
  • Annual Expenses: ~$63,400 (mortgage repayments, ATO payments, living costs)
  • Estimated Borrowing Capacity: $200,000–$300,000
  • Required Loan Size: Approximately $520,000 to purchase a $650,000 property

Top 5 Strategies to Increase Borrowing Power

  1. Eliminate ATO Debt
    By paying $1,000 per month, Sally can clear her $20,000 tax debt in under two years. Reducing this liability will improve her serviceability and demonstrate fiscal responsibility to lenders.
  2. Leverage Home Equity
    Using Home Equity With around $510,000 in equity, Sally can refinance her existing loan to extract $100,000. This additional cash can cover a deposit and any lender’s mortgage insurance (LMI).
  3. Stabilise and Grow Your Income
    Maintaining or increasing her $120,000 earnings into 2026 will strengthen her application. Providing detailed business financials and BAS statements can further reassure lenders of her income stability.
  4. Commit to Regular Savings
    If Sally saves $1,500–$2,000 per month, she can accumulate the required $65,000 deposit within 2.5 to 3 years, reducing her reliance on LMI and improving her loan-to-value ratio.
  5. Engage a Specialist Mortgage Broker
    A broker with expertise in self-employed lending can identify lenders with flexible policies, structure her application around equity and income growth, and negotiate competitive rates.

Conclusion

By systematically clearing debt, tapping into equity, boosting income, and saving consistently—backed by professional advice—Sally can position herself to purchase a $650,000 property within 12–24 months.

Talk to a mortgage strategist today and turn your home-buying aspirations into reality.
@

Retire without working another decade? Property makes it possible. Rents rise. Debt shrinks. Equity stacks. Play it smart — and let your assets do the heavy lifting. #creatorsearchinsights #retireearl...

@

You see a living room — they see lending leverage. Property investing isn’t about vibes, it’s about structure. Know your LVR. Extract equity. Play the bank’s game better than they do. #LendingLev...

@

Feel like you’ve been knocked out by the tax man? You’re not alone — but the wealthy don’t just sit there dazed. They fight back with strategy. They buy new builds — for maximum depreciation, generou...

You may also like

Related posts

The Ultimate Guide to Property Investing in Australia (2025)

The Ultimate Guide to Property Investing in Australia (2025) Property investing in Australia remains one of the most reliable ways to build wealth, but with rising interest rates, changing market trends, and shifting government policies, investors need to be well-informed. Whether you’re a first-time buyer or a seasoned investor, this...

Mar 23rd, 2025
1 year ago
How George and Yasmin Can Use Their SMSF to Buy Property: Strategy & Structure Explained

How George and Yasmin Can Use Their SMSF to Buy Property: Strategy & Structure Explained George and Yasmin have no personal savings and a high debt load, yet they hold $250,000 in superannuation. By setting up a Self-Managed Super Fund (SMSF) and using a limited recourse borrowing arrangement (LRBA), they...

Jul 24th, 2025
1 year ago
What Happens When You Turn Your Home into an Investment Property in Australia (2025 Guide)

Should You Switch Your Home Loan When Renting Out Your Home? Considering renting out your principal place of residence (PPOR) in Australia? It’s not just about finding tenants and collecting rent. There are important financial and legal factors to consider, especially concerning your mortgage. Why You Need to Update Your...

May 25th, 2025
1 year ago
Straightforward process

Ready to take control of your financial future?

01
Discovery Q&A:

We begin with a personalized discovery Q&A to understand your goals, risk tolerance, and financial situation.

02
Custom Strategy:

Based on your needs, we craft a strategic investment or financial plan tailored just for you.

03
Ongoing Support:

We help you track progress, optimize decisions, and adjust your plan as your life and markets evolve.

04
Financial Freedom:

With a clear roadmap and expert guidance, you move confidently toward long-term wealth and peace of mind.

28+ Years guiding investors
Plan Your Investment Strategy

Understand your goals and build a tailored strategy—whether you're focused on cashflow, capital growth, or long-term wealth creation.

Access the Right Opportunities

Explore high-growth areas, new builds, house & land packages, or SMSF-ready properties matched to your financial profile.

Build Long-Term Wealth

Leverage tax advantages, depreciation, and smart lending strategies to maximise returns and grow your portfolio sustainably.

Start Your Investment Journey

Smart Property Investing Starts Here

Whether you're a first-time investor or growing your portfolio, we provide the guidance, tools, and insights you need to make informed decisions and secure high-performing properties. Let us help you turn property into prosperity.