Deciding Between SMSF and Personal Lending for Property Investment
Choosing whether to acquire property through a Self-Managed Super Fund (SMSF) or via a personal loan hinges on your financial objectives, risk tolerance, tax position and retirement planning. Below is a concise guide—based on 2025 market conditions and regulations—that outlines when an SMSF structure is advantageous and when personal lending could be a better fit.
When an SMSF Is the Better Choice
-
Tax-Efficient Retirement Strategy
SMSF rental income is taxed at 15%, with capital gains at 10%. Once in pension phase, gains may even become tax-free—ideal for high earners looking to minimise long-term tax liabilities. -
Sufficient Super Balance
You generally need a superannuation balance of $150,000–$200,000 to cover deposits, buffers and SMSF running costs. Rental income plus concessional contributions can service the loan. -
Commercial Property for Your Business
SMSFs may buy business real property and lease it back to your own company at market rates. Note: residential properties cannot be used by members or related parties. -
Direct Investment Control and Diversification
SMSFs offer direct ownership of bricks-and-mortar, diversifying a portfolio typically weighted towards equities and fixed interest. -
Limited Recourse Borrowing Arrangement (LRBA)
You can borrow up to 70–80% LVR for residential or 60–70% for commercial, with recourse limited to the property alone—protecting other SMSF assets. -
Strong Long-Term Growth Outlook
If your horizon is 10+ years and you believe in property’s capital growth, an SMSF provides a strategic, tax-wrapped vehicle.
When Personal Lending Makes More Sense
-
Owner-Occupier or Family Leasing
SMSF rules prohibit personal use or leasing to related parties. A personal loan lets you live in the property or lease it to family. -
Limited Superannuation Balance
With under $150,000 in super, SMSF setup and compliance costs often outweigh benefits—personal lending is more practical. -
Negative Gearing Opportunities
Losses on an investment property can offset your personal taxable income. SMSFs cannot claim negative gearing against other income streams. -
Easier Access and Lower Rates
Personal borrowers have wider lender choice, interest rates around 4–5% versus 6.7–7.2% for SMSFs, and faster approvals. -
Greater Flexibility
Selling or repurposing a personally owned property is simpler—no sole-purpose test or superannuation compliance hurdles. -
Avoiding Compliance Complexity
SMSFs require annual audits, ATO reporting and strict adherence to super rules. Personal ownership avoids these administrative burdens.
2025 Strategy Notes
- Interest Rates: June 2025 RBA rate cuts have reduced borrowing costs.
- Market Outlook: Residential prices peaked in April 2025; commercial assets remain stable.
- Regulatory Watch: SMSF lending faces tighter scrutiny and fewer lender options; personal lending remains more flexible.
Verdict
Choose an SMSF if you have a substantial super balance, seek tax advantages, and plan to hold property for the long term.
Opt for Personal Lending if you want immediate use, family leasing, negative gearing benefits or greater flexibility.
Not sure which path suits you? Speak with a qualified financial adviser or SMSF specialist to align your borrowing power with your retirement vision.
Visit our property investment chat to assess your lending potential and craft a strategy for financial success.
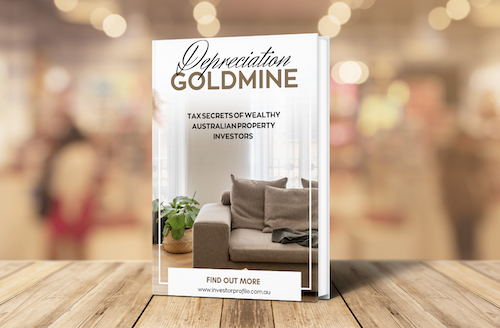
Discover the #1 tax secret wealthy Australian property investors use to grow their portfolios faster — even in a high interest rate environment.
- Learn how to turn wear and tear into wealth
- See real examples of $15,000+ first-year deductions
- Understand how to structure your purchases for maximum after-tax ROI
Download Your Free Wealth Building Guide
This ebook reveals how to legally slash your tax bill while building long-term wealth through property. Learn the strategies savvy investors use to gain an edge — even before settlement.
- Maximise tax deductions and improve cash flow
- Understand Division 40 vs 43 and how to claim both
- Position yourself to reinvest and scale faster